Only one in 10 Australian financial advisers rate their business processes as efficient, even as more than 80% of advice firms now use artificial intelligence (AI). The figures come from the Australian Advice Efficiency Survey by adviser technology provider intelliflo.
The research also found fewer than half of firms have formal policies governing their use of AI.
File notes are the most common application, ahead of advice document generation and client engagement. Most advisers also see accountability as sitting in-house, with more than half saying responsibility for errors made by AI tools ultimately rests with the advice business.
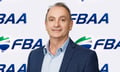
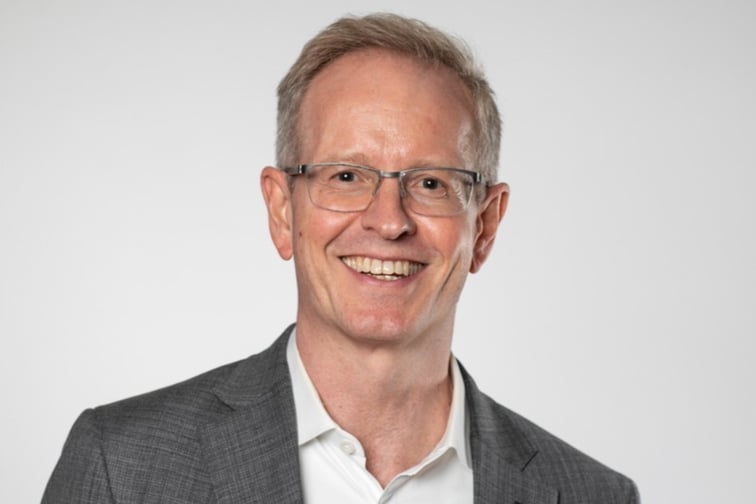
“AI has firmly entered the mainstream of financial advice,” said Nick Eatock (pictured), chief executive and co-founder of intelliflo.
He warned, however, that oversight has not kept pace. “The speed of AI adoption is outpacing the development of governance frameworks inside many advice businesses,” Eatock said.
Brokers face a similar gap. A Connective survey of more than 300 brokers found only 3% had formal policies for safe AI use, while 65% had no documented AI strategy.
The intelliflo survey, conducted in May, found 90% of advisers hold a neutral or negative view of their operational efficiency. Four in five firms have automated less than half of their workflows, yet 80% would like to automate at least half of them.
Client onboarding and the preparation of Statements of Advice (SOAs) and Records of Advice (ROAs) topped the list of tasks advisers most want automated.
Client expectations are shifting too. Nearly three-quarters of advisers now run a hybrid model, meeting clients both virtually and in person. Secure communication, digital onboarding, workflow automation, and system integration ranked among the most requested technology improvements.
Almost half of respondents said adviser capacity was the single biggest obstacle to growing their client base. Technology limitations ranked second among constraints on business growth. Only a small minority believed an adviser could sustainably look after more than 250 clients under their current operating model.
Eatock said Australia has approximately 15,000 financial advisers serving millions of people who need help with financial decisions.
“Technology alone won’t solve the capacity challenge, but it is one of the most powerful levers available to the profession,” he said.
He added that firms combining technology, efficient processes, and strong governance would be best placed to grow as regulatory reform continues.
Get the hottest and freshest property and mortgage news delivered right into your inbox. Subscribe now to our FREE daily newsletter.