Australian mortgage demand dropped 19.2% year on year in September 2026, the sixth consecutive monthly decline and the weakest result since October 2022, according to the Equifax Consumer Market Pulse.
The result reversed a brief improvement in August, when demand was down 14.1%.
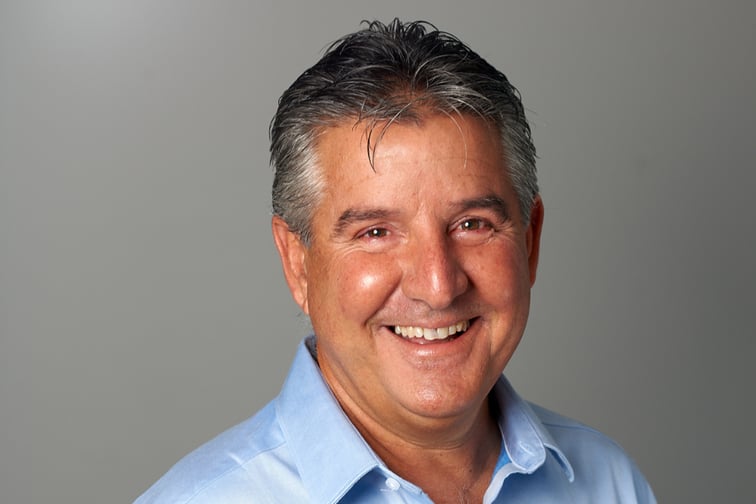
Kevin James (pictured), chief solution officer at Equifax, said that in a sustained high-rate environment “Australian households are taking a decisive step back”.
Demand weakened in every state, with NSW (21.2%) and the ACT (21%) recording the steepest falls. Younger borrowers drove much of the decline: applications from 18 to 25-year-olds were down 25%, and those from 26 to 35-year-olds declined 22.5%. Demand among potential investors, meaning borrowers with two or more mortgages, also dropped 18%, following an 11.4% fall in August.
Refinancing activity, a key source of broker business, also slowed. Switching to a different lender declined 8.8% year on year after an almost flat result in August, while refinancing with an existing lender dropped 28%.
According to James, strict serviceability assessments appeared to be stopping many borrowers from moving, even when they wanted a better rate, “effectively locking them into their current arrangements”. The pressure is showing up in official data: minutes of the Reserve Bank’s (RBA) September meeting show scheduled mortgage repayments have climbed to about 10% of household disposable income, near their 2024 peak.
Switching demand varied by age, rising 3.2% among 56 to 60-year-olds and 2.3% among those over 60, while falling 14.2% among 26 to 35-year-olds.
First-home buyer applications fell 22.1% year on year, the largest annual decline since December 2022. The fall has worsened each month since July, from 19.2% in July to 20.1% in August.
James noted that the contrast with strong first-home buyer activity in late 2025 showed “the gap in market entry is widening significantly”. The average first-home buyer loan remains at a record $743,000.
He said elevated prices, strict serviceability testing, high interest rates, and cost-of-living pressures were making it harder for younger buyers to cover both the deposit and the repayments without help from family or other sources.
Recent price falls have so far done little to change that: national home prices have fallen for six straight months but remain just 3.3% below their March 2026 peak.
Unsecured credit moved the other way. Credit card demand rose 10%, which James linked to applicants aged 56 and over switching cards ahead of the RBA’s 1 October interchange fee changes.
Get the hottest and freshest property and mortgage news delivered right into your inbox. Subscribe now to our FREE daily newsletter.