Pitcher Partners Sydney Private Wealth expects the Reserve Bank (RBA) to lift the cash rate once more by early 2027, as tighter policy and the 2026–27 federal budget’s property tax changes weigh on mortgage demand.
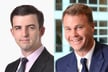
In its Economic and Market Outlook for October 2026, the firm said “the likeliest scenario is one more rate hike by year-end or early 2027”. After that, it expects the cash rate to stay on hold. The outlook was written by chief investment officer Cameron Curko and partner Martin Fowler (pictured left to right).
The RBA raised the cash rate by 25 basis points to 4.6% on 29 September. Underlying inflation was 3.6% in the year to August, still above the central bank’s 2–3% target band. Market pricing pointed the same way in the near term: minutes of the RBA’s September meeting show markets expected roughly another 15 basis points of tightening by the end of 2026. Bloomberg forecasts in the outlook put the cash rate at 4.6% for 2026 and 4.3% for 2027.
Mortgage demand is already slowing. Citing Australian Financial Review reporting, the outlook said mortgage applications fell by between 12% at ANZ and 20% at Westpac after the budget curbed negative gearing and raised capital gains tax.
With fewer new loans to go around, Curko and Fowler warned “competition for new mortgages is likely to intensify”. They expect this to keep pressure on bank margins until investor confidence recovers.
National home prices fell for a sixth straight month in September and are now 3.3% below their March 2026 peak, according to the latest realestate.com.au Home Price Report.
Commercial finance is moving the other way. Business credit grew 10.6% in the year to July 2026, well ahead of the 7.4% growth in housing credit. Pitcher expects investment spending and a solid pipeline of housing construction to keep overall credit growing.
The firm cautioned that this strength could fade if higher rates slow the economy, noting that “business lending is inherently more cyclical”.
RBA estimates cited in the outlook suggest a 10% fall in house prices could reduce growth by around 0.8% after six months and by up to 1.6% over the medium term. Among the supports Pitcher expects to cushion household spending are population growth of 1.4% and superannuation benefit payments, which reached $148 billion in the year to June 2026.
The economy grew 2.1% over the same period. However, the authors pointed to weak productivity as a structural reason inflation is proving hard to shift.
Get the hottest and freshest property and mortgage news delivered right into your inbox. Subscribe now to our FREE daily newsletter.