Australia’s banking system and most mortgage holders are coping with a weakening housing market, but the prudential regulator says high household debt remains a key weak spot. It is also watching lending standards closely as lenders compete harder for borrowers.
The warnings come in the twice-yearly System Risk Outlook from the Australian Prudential Regulation Authority (APRA).
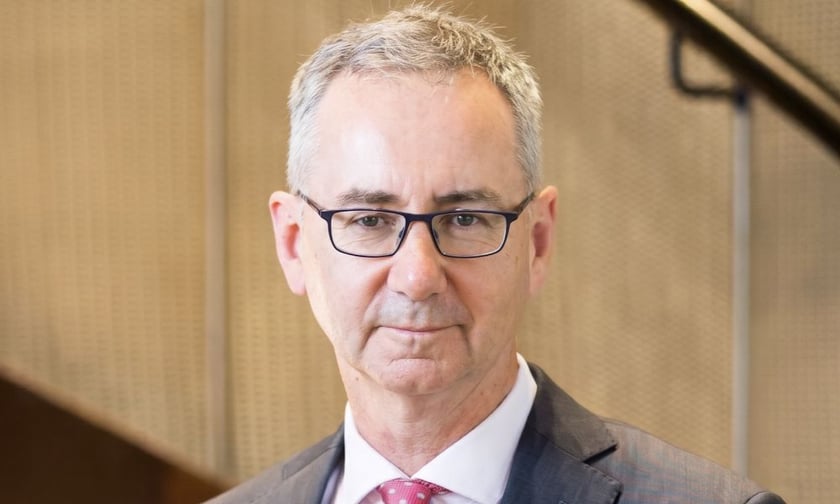
“Australia’s financial system remains resilient, but the risk environment is becoming less forgiving,” APRA chair John Lonsdale (pictured) said in a statement accompanying the report.
According to APRA, national home prices have fallen by about 6% since March, back to roughly mid-2025 levels. Higher interest rates, tax changes and weaker sentiment have all weighed on demand. Housing credit growth has slowed, most noticeably among property investors, though it remains above its long-term average. Forward indicators suggest activity will ease further.
New lending figures from the ABS underline the pullback. Home lending recorded its biggest quarterly fall on record in the September quarter, led by investors, while first-home buyer loans dropped 8.6%
Even so, many borrowers have built up sizeable equity and prepayment buffers. Citing Reserve Bank estimates, APRA said fewer than 2% of variable-rate owner-occupiers face a cash-flow shortfall, and fewer than 1% of all borrowers are in negative equity. Mortgage arrears have risen but remain low. CBA, the largest lender, reported in its first-quarter update that home loans at least 90 days overdue had climbed to 0.80%, a six-year high.
The concern is the overall level of debt. Household debt sits at around 180% of disposable income, high by both historical and international standards. APRA warned that this “could amplify a more severe downturn”, particularly if a sharper fall in prices coincided with a substantial rise in unemployment or tighter credit conditions.
With the market slowing, APRA said it was working with the other Council of Financial Regulators agencies to watch for signs that competition, both between banks and from non-bank lenders, is eroding lending standards. Riskier lending is contained for now, and the limits on high debt-to-income loans introduced in February 2026 continue to act as a safeguard.
Beyond housing, APRA pointed to long-term government bond yields in advanced economies, which are near their highest in at least 15 years. A disorderly adjustment could raise funding costs for Australian institutions and, in turn, borrowing costs for households and businesses.
Stress testing offers some reassurance. In a joint trans-Tasman exercise, the largest Australian and New Zealand banks kept lending through a deep recession scenario.
“Our financial system is well placed to withstand this turbulent period,” Lonsdale said.
Get the hottest and freshest property and mortgage news delivered right into your inbox. Subscribe now to our FREE daily newsletter.