Mortgage brokers who suspect a client’s documents have been altered should halt the application, record their concerns, and escalate through compliance channels, Australia’s two main broker associations said, as AI-generated paperwork puts loan verification under the spotlight.
The guidance from the Mortgage & Finance Association of Australia (MFAA) and the Finance Brokers Association of Australia (FBAA) follows an OurTop10 survey in which 18% of 1,018 Australians said they had used AI to create or alter home loan documents.
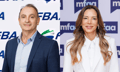
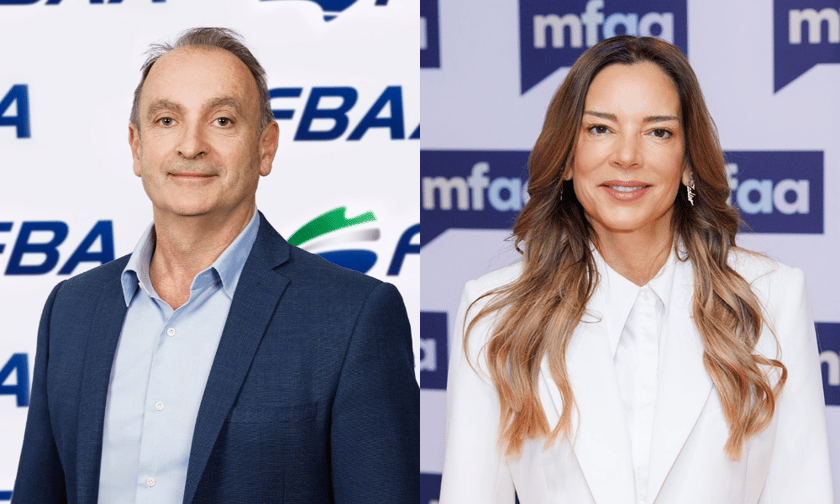
Leo Gagic (pictured left), chief executive of the FBAA, said the association could not independently verify the 18% figure, but it was consistent with broker feedback that document integrity and fraud detection had become harder in recent years. He stressed that most brokers do the right thing.
MFAA chief executive Anja Pannek (pictured right) said members had raised concerns about sophisticated scams and data integrity, though the association’s research does not measure any rise in AI-altered documents.
Gagic said brokers were reporting metadata that does not match the claimed source, formatting oddities such as unusual fonts or spacing, inconsistencies between documents, and documents that look unusually clean or lack expected transaction history. He advised brokers not to rely on any single document in isolation.
The MFAA released its referrer risk guidance this week, developed with major aggregators and lenders through its Fraud and Referrer Working Group. It flags similar issues, including unverifiable documents, unexplained discrepancies, and the same supporting information reappearing across applications. Referrals account for 40% of broker business leads, according to Deloitte research for the association.
Pannek said a client who cannot explain their application, or a referrer who limits direct contact, should also prompt questions, though such signs do not on their own prove fraud or AI involvement.
Both bodies urged brokers not to proceed on suspect information.
“Brokers should pause, record the concern and follow their compliance or fraud escalation process,” Pannek said.
That means keeping the original documents, seeking independent verification, involving the licensee’s or aggregator’s compliance team, and raising concerns promptly with the lender if an application has already been lodged.
Gagic said brokers should also keep clear file notes of their concerns and actions.
The regulator is also watching closely. The Australian Securities and Investments Commission (ASIC) warned in May that AI is lowering the barriers for cybercriminals, and has since named fraud among its 2026–27 priorities and flagged a review of lender oversight of brokers and referrers.
Both associations support consumer-consented digital verification. The MFAA backs access to relevant Australian Taxation Office income data with client consent, alongside wider use of the Consumer Data Right, noting that brokers facilitate 81.6% of new residential home lending.
The FBAA said open banking and similar tools should complement, rather than replace, brokers’ professional judgement.
AFG’s Christa Malkin made a similar point last week, cautioning that source data can confirm a client’s numbers without showing the full story behind them.
Gagic said fraud prevention must be shared across the lending chain. Brokers play a critical frontline role, he said, but “they should not be expected to carry the burden alone”.
That echoes SFG’s Blake Buchanan, who said last week that handing paperwork to a lender does not relieve brokers of their duty to verify it.
The MFAA has also called for a national mortgage fraud summit to improve verification and information sharing.
Get the hottest and freshest property and mortgage news delivered right into your inbox. Subscribe now to our FREE daily newsletter.