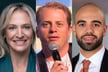
Australia’s co-living sector could almost triple in size by 2030, as international investors move in and new markets open up beyond Sydney, according to Savills Australia’s inaugural co-living report.
Around 4,700 co-living units are now operating across Australia, according to Savills. That’s expected to reach about 6,300 by the end of 2027 and could climb above 13,700 by 2030 if every scheme in the current pipeline proceeds.
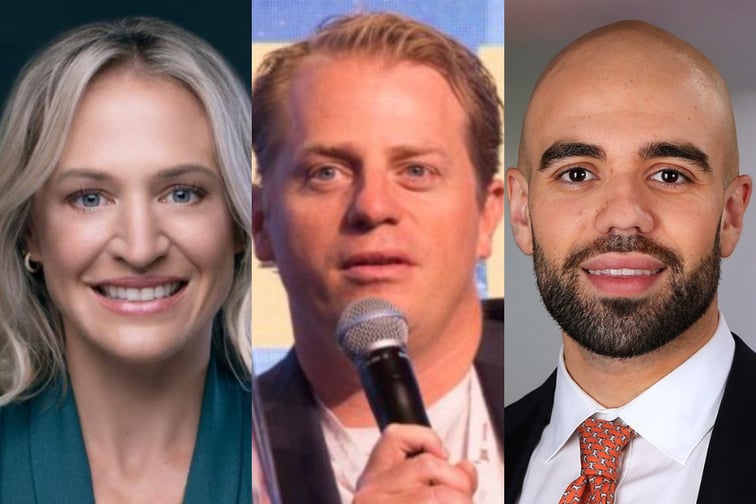
“Australia’s Co-Living sector is still early in its institutional development, but offshore capital has moved well beyond curiosity,” said Emily Fell (pictured left), senior director, capital markets – living sectors at Savills Asia Pacific.
The growth comes as renters face sustained pressure. Savills cites Cotality data showing rents rose 5.5% nationally in the year to September 2026, with rental households spending around 34% of pre-tax income on rent, the highest share on record. Separate PropTrack data shows advertised rents reached a record $675 a week in September 2026, although the national vacancy rate has edged up to 1.5%.
With high house prices and deposit hurdles keeping more Australians renting for longer, the tenant base is broadening. Data from UKO, Australia’s largest co-living operator, shows one in five of its tenants is over 35.
“Co-Living is becoming widely recognised as a genuine housing solution for singles and young professionals,” said UKO founder and managing director Rhys Williams (pictured center).
Savills found co-living rents across two sample Sydney assets were 12% cheaper than the all-in cost of renting a one-bedroom apartment in the surrounding suburbs, once utilities and furniture are included.
Income-producing co-living assets have traded at yields of 4.5% to 5.7%, a premium to build to rent and broadly in line with purpose-built student accommodation. Savills said operating assets are typically selling within four to five weeks.
Savills director Adrian Bokolis (pictured right) said the sector’s “structural demand drivers and constrained supply make the investment case increasingly difficult to ignore”.
The trend extends across the living sectors. JLL found foreign capital made up 74% of Australian student housing acquisitions in 2025.
Schemes are also getting larger. Projects under construction average 94 units, nearly double the 48-unit average of completed schemes.
Sydney accounts for 79% of operational supply and 82% of the pipeline, helped by New South Wales being the only state with a dedicated co-living planning framework. Based on 26 rental, demographic, and economic indicators, Savills ranks Melbourne, Brisbane, and Perth as the strongest growth markets beyond Sydney.
For brokers with property investor clients, the report also flags that changes in the May 2026 federal budget could make the tax environment less favourable for some small-scale landlords. That may reduce investment in established rental stock and add to demand for purpose-built alternatives.
Read the Savills Co-Living report.
Get the hottest and freshest property and mortgage news delivered right into your inbox. Subscribe now to our FREE daily newsletter.