The last variable mortgage rates below 6% are set to vanish after the Reserve Bank of Australia (RBA) lifted the cash rate to 4.85% on 3 November 2026, its fifth increase this year, according to Canstar.
The gap between back-book and competitive mortgage rates is also widening. Canstar estimates an owner-occupier who took out a variable loan five years ago and hasn’t renegotiated could soon be paying around 7.34%, while competitive rates should stay below 6.5%.
A new Canstar survey of 1,012 Australian adults, conducted in November, found 10% of mortgage holders say they won’t be able to cover the higher repayments. Another 28% said the increase would be a struggle, and 41% said they would need to cut back on spending. Only 21% said they could manage comfortably.
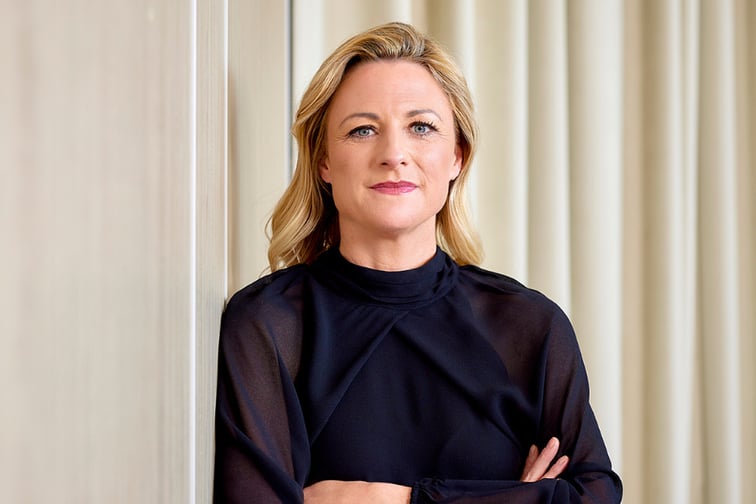
“There’s a growing divide between borrowers who can absorb another rate hike and those who simply can’t stretch their budgets any further,” said Sally Tindall (pictured), Canstar’s data insights director.
Renters are feeling it too. More than two-thirds (68%) said they were concerned the decision would make rent or living costs harder to manage.
Fixed rate activity before the decision was unusually quiet. Only one lender, The Mac, lifted select fixed rates, by an average of 0.14%. Canstar’s weekly tracking showed eight rates below 6% before the announcement, down from 12 the previous week.
“In the lead-up to an RBA hike, we usually see more than a flurry of fixed rate rises, in fact, it’s usually a snowstorm,” Tindall said.
EMBED: 11 03 Canstar
EMBED: 11 03 Canstar 2
Macquarie Bank was first to respond after the decision, confirming it will pass the full increase on to variable borrowers from 19 November. The big four banks hadn’t confirmed their moves when Canstar released its figures, but are expected to follow on 13 November. Borrowers typically get two to three months’ notice before their repayments rise.
Canstar estimates the increase will take the average owner-occupier variable rate to 6.74% and the lowest to 6.18%.
For brokers, the gap between back-book and competitive rates is the main opportunity. On a $600,000 loan with 25 years left, switching from 7.34% to 6.49% could save just over $9,000 over two years, even after $1,150 in switching costs, Canstar calculates.
Not every borrower can make the switch. Higher rates, sliding property prices, or changed circumstances may leave some unable to refinance, Canstar said. For them, it suggests asking their current lender for a rate review and getting in touch early if they expect to miss a repayment.
“It’s expected refinancing activity will continue to gather pace, however, some borrowers may need help getting out of mortgage prison,” Tindall said.
Get the hottest and freshest property and mortgage news delivered right into your inbox. Subscribe now to our FREE daily newsletter.