Australia's mortgage market is splitting sharply along generational lines. Equifax's Consumer Market Pulse for August shows Australians aged 56 and over driving a rebound in credit card and personal loan demand, even as under-35s pull back across every credit category – nowhere more starkly than in the collapse of first-home buyer lending.
Credit card applications returned to growth for the first time in four months in August, up 2.9% year-on-year (up from -1% in July), while personal loan demand rose 1.3%.
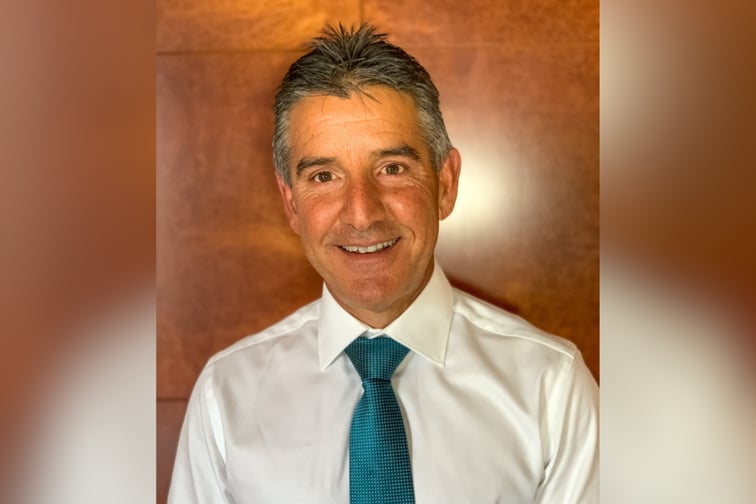
Equifax chief solution officer Kevin James (pictured) said the credit card rebound could be linked to broader changes across the banking landscape ahead of the RBA's 1 October interchange fee cap reduction, with financial institutions notifying cardholders of upcoming changes to rewards earn rates, points caps, and annual fees – prompting consumers to shop around for better value before the deadline.
That growth was concentrated almost entirely among Australians aged 56 and over, with credit card enquiries in that age group up 21.5% and personal loans up 14.7%. James noted this cohort typically holds greater housing equity and lower relative leverage, and may be drawing on credit facilities for liquidity, reward optimisation, or home improvements.
Younger Australians told the opposite story, retreating across mortgage, credit card, and personal loan demand alike.
Overall mortgage commitments remained down 14.1% year-on-year in August, but the more striking move was in first-home buyer lending, which fell 20.1% nationally – the steepest annual decline recorded since 2022. New South Wales (-22%) and Queensland (-22.6%) led the retreat.
James said the market is "adjusting to a sustained higher interest rate environment," with many borrowers expecting at least one more rate rise before year's end. That expectation lines up with the big four banks, which have all now shifted to forecasting a further RBA rate rise before year-end. He described the first-home buyer decline as "the largest year on year decline we've seen among FHBs since 2022," pointing to affordability limits and market uncertainty as key drivers.
The supply side tells a similar story: separate HIA data shows new home sales fell 10% nationally in August, with HIA managing director Tim Reardon warning the market "cannot absorb further interest rate increases" on top of this year's tax changes.
Refinance switching, which had fallen sharply in July, nearly returned to flat territory in August, down just 0.8% year-on-year. Western Australia and Queensland both moved back into positive growth, up 2.3% and 1% respectively.
James said this reflected borrowers becoming more active in seeking better deals, noting "where value can be unlocked, Australians are moving to secure it."
Get the hottest and freshest property and mortgage news delivered right into your inbox. Subscribe now to our FREE daily newsletter.