As market chatter intensifies around potential interest rate hikes, first-time homebuyers are among those feeling the most anxiety.
New research commissioned by the Mortgage & Finance Association of Australia (MFAA) and YouGov has highlighted just how much support would-be buyers may need as they navigate an increasingly uncertain lending environment.
The report found that two out of five Australians who are planning to enter the home loan market for the first time within the next three years lack confidence when it comes to navigating the home loan market. Of the 2,057 surveyed, many say they need expert guidance, including support from a mortgage broker, to help them understand their options.
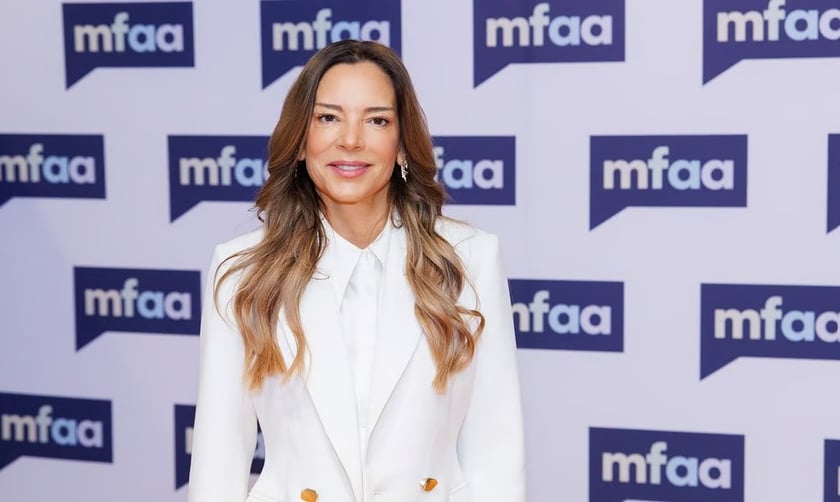
"For a first-time homebuyer, a rate rise isn't just about higher repayments. It can also affect borrowing capacity," said Anja Pannek, chief executive officer of the MFAA. "As interest rates rise, the rate lenders use to assess serviceability generally rises too, which can reduce how much a buyer is able to borrow."
In fact, if rates go up, a $600,000 mortgage would tack on an additional $100 a month in repayments. It would also reduce the borrower's borrowing capacity by roughly $13,000.
"For buyers already near their limit, that can make a meaningful difference. A home that fitted the budget last month can suddenly sit just out of reach," Pannek told Australian Broker. "That’s why the question we hear most isn’t just what the Reserve Bank will do next. It’s: ‘How much can we actually borrow now?'"
Pannek's comments come as expectations of another rate hike continue to gather momentum across the market. Earlier this week, the last of Australia’s Big Four banks updated its interest rate forecast, bringing all four major lenders into agreement that another hike would most likely come at the Reserve Bank of Australia’s (RBA) 28 to 29 September monetary policy meeting.
Meanwhile, other signs of looming rate hikes abound. Rate expectations have also begun to filter through into lenders’ pricing decisions, with Commonwealth Bank of Australia (CBA) raising its one-year fixed home loan rate on Tuesday. The move signals that major lenders are already factoring prospect rate hikes into their lending strategies.
Pannek said that if rates do go up "Every buyer will respond differently. Some may delay their purchase or build a larger deposit, while others may consider a smaller property, a different location or a revised timeframe. Our members are seeing first-time homebuyers reconsider their expectations, including looking at apartments, smaller properties or more affordable locations. Others are taking longer to build their deposit.
"These decisions are personal," she added. "A broker can help buyers understand the options available and find an approach that supports sustainable homeownership without placing unnecessary pressure on their household budget."
The nation's central bank has already raised the official cash rate (OCR) three times in 2026, lifting rates to their current level of 4.35%. A further increase would add another layer of pressure for mortgage holders and property investors across the country, many of whom are already contending with elevated living costs and persistent inflationary pressures.
Borrowers are also having to navigate the impact of new tax regulations following the updated budget, reduced borrowing capacities and a broader backdrop of economic uncertainty. For prospective and existing homeowners alike, another rate rise could therefore have implications extending well beyond the immediate increase in monthly mortgage repayments.
"The biggest challenges I'm seeing right now are servicing and fear of rates going up," said Caroline Jean-Baptiste, a mortgage broker with Mortgage Choice and newly-appointed MFAA Life Member. "Cost of living is squeezing budgets, and buyers are finding it hard to secure a property within their capacity in the areas they want to live.
"Deposits are the other hurdle," she continued. "A lot of buyers have saved just under 5%, and very few lenders will count gifted funds as genuine savings when someone has been living at home rent free or sharing with friends without a lease."
With borrowers facing a more uncertain rate environment and tighter affordability constraints, brokers have an important role to play in helping buyers understand how changes in lending conditions could affect their plans.
"Brokers should help buyers understand what they can afford now and what their budget could look like if rates rise again," Pannek said. "That includes modelling different scenarios, building in a repayment buffer and explaining the range of lenders, products and government schemes available.
"Even when rates are on hold, it is not a time to sit still," the CEO added. "Buyers should continue speaking with their broker, reviewing their borrowing capacity and preparing for different scenarios. Falling property prices may also bring previously unaffordable properties or suburbs within reach."