A new lender has been added to the Help to Buy panel, bringing another bank into the fold for brokers to consider when writing eligible loans.
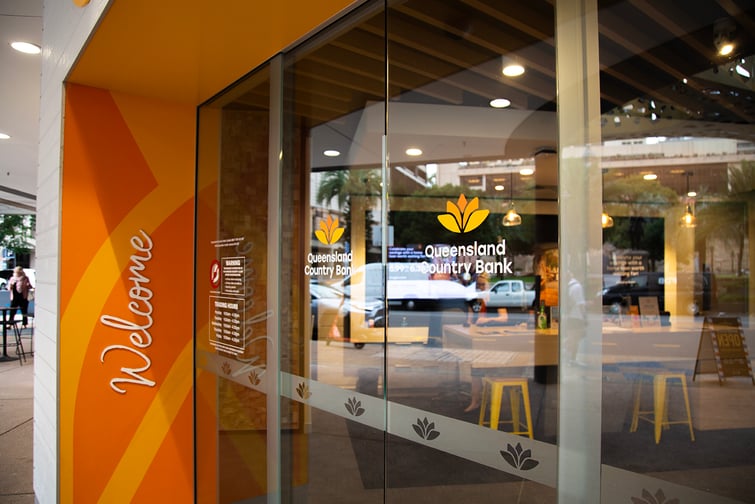
Queensland Country Bank, a member-owned mutual, has joined the federal government’s Help to Buy lending panel, effective this month. Aspiring homeowners are now able to access the scheme through Queensland Country's retail and broker channels.
Queensland Country’s entry comes as the scheme continues to broaden its lender network, giving brokers more choice when evaluating borrowers who may benefit from the government’s contribution towards a home purchase.
Aaron Newman, chief executive officer of Queensland Country Bank, said the lender's decision to participate reflects the role it sees itself playing in assisting members in becoming homeowners.
“Helping people own their homes is core to who we are as a member-owned bank," Newman said in a public statement.
“Housing affordability continues to be a real challenge," he continued. "This initiative reduces the upfront deposit barrier, supporting eligible members to enter the market sooner, while maintaining a strong focus on long-term affordability and financial wellbeing.”
Customer-owned Queensland Country Bank, which was founded in the regional Queensland town of Mount Isa in 1971, has more than 100,000 members. The bank is the second lender to join the government’s scheme since the inaugural panel was established with Commonwealth Bank of Australia (CBA) and Bank Australia.
Teachers Mutual Bank Limited was added to the panel in July, initially making Help to Buy available directly through Teachers Mutual Bank, Health Professionals Bank, UniBank and Firefighters Mutual Bank. Earlier this month, the lender’s first broker cohort completed the training required to offer the scheme, with broader broker access expected to follow in 2027.
Queensland Country's appointment now gives brokers another avenue through which to facilitate Help to Buy loans. CBA remains the only lender on the panel that does not offer the scheme through brokers.
The expansion of the panel has been welcomed by brokers, who have generally viewed the addition of lenders as a positive development for the scheme.
"Previously, I didn't have a lender on my panel that I could help under that scheme," Luke Ashby, finance specialist and mortgage broker at Brisbane-based Emerge Finance, told Australian Broker. "But now Teachers Mutual Bank is available to brokers. So that's great news."
James Green, director and finance broker at Flint Group in Brisbane, agreed it's "definitely a good thing.
"The more lenders in that space that brokers can utilize, the better; the client is going to get a better experience," he said. "In the first-time homebuyer space, in particular, you're dealing with a clientele which doesn't always have a whole lot of knowledge or experience with transactions. There have been a few times where clients have gone direct to a bank, but then they reach out because they want that more handholding experience. Because when you take that first step in purchasing your first property, there's a lot of education and handholding involved."
The Help to Buy shared equity scheme launched on 5 December 2025. The program allows for up to 40,000 eligible Australians to jump on the property ladder over the next four years by way of the government's national housing authority Housing Australia.
Under the scheme, borrowers can purchase property with as little as a 2% deposit. The government contributes 40% of the purchase price for new homes, or 30% of existing homes for eligible owner-occupiers with a mortgage. No ongoing, regular payments are required, but homeowners can repay the government shares by making regular payments or selling the home in order to increase their equity in the property.
To qualify, individual borrowers must not make more than $103,000 annually, or $165,000 for joint applicants. Both first-time buyers and existing homeowners can apply for the program. Spaces are limited; 10,000 borrowers will be selected each year. Housing price caps are determined by local markets.
While the expansion of the lender panel has been welcomed by brokers, CBA remains the only participating lender that has not made Help to Buy available through the broker channel.
"It's frustrating," Ashby said. "For Commonwealth Bank to be on the scheme, but not allow brokers to write the deals. It's very disappointing. [Access to the scheme] has to go through a direct channel only, which, obviously, if they really cared about helping homebuyers, they would make it available to brokers to write, as well. Hopefully that changes.
"It'd be great to see some more lenders jump on the panel," the broker added. "It'd be great to see CommBank open up the door to brokers to write those deals under their brand."
Green agreed that his experience with the panel has been "frustrating."
"There have been some instances where we have had to refer out," he explained. "At the end of the day, we have to operate under the best interest duty (BID), the client's best interest. And even though that's not on our panel, there have been some instances where you've got to do the right thing, and I have referred clients to that bank for that reason.
"It is always frustrating, obviously, when you've got relationships, but you don't have access to products," Green continued. "It would be good to open that up. With the volume of loans brokers are writing, the more tools you have in your belt, the better you can serve that clientele. It is difficult when you know that their policy and that product is the best for the client, but you don't have access to it."
CBA declined to comment for this story.
But CBA's General Manager Third Party Banking Baber Zaka has told Australian Broker when the scheme first launched that "mortgage brokers play an important role in supporting home ownership in Australia, particularly for first-time homebuyers who are navigating the process for the first time.
"The Australian government's Help To Buy scheme is in its early stages, with a limited number of placements. While not currently offered through the broker channel at CBA, we continuously review our distribution strategy and that might change in the future," Zaka continued. "Our focus remains on helping customers to achieve their home ownership objectives and on supporting brokers through investing in innovative technology and comprehensive systems that make working with CBA seamless and industry leading."