Australia's property markets continue to face higher interest rates, inflationary pressures, falling property prices and buyer uncertainty, all creating an increasingly challenging environment for buyers and brokers alike.
For Australian Broker's latest Spotlight Series — where we highlight standout players across Australia's finance and broking industries — we caught up with Chris Brown, founder and chief executive officer of New Vision Group, for his thoughts on the current landscape.
"The RBA increased the cash rate in September. The latest ABS figures show annual headline inflation and trimmed mean inflation are up," Brown told Australian Broker. "Those conditions reinforce the importance of building some breathing room into a borrowing decision."
With nearly 30 years of industry experience, Brown brings a wealth of knowledge to the conversation.
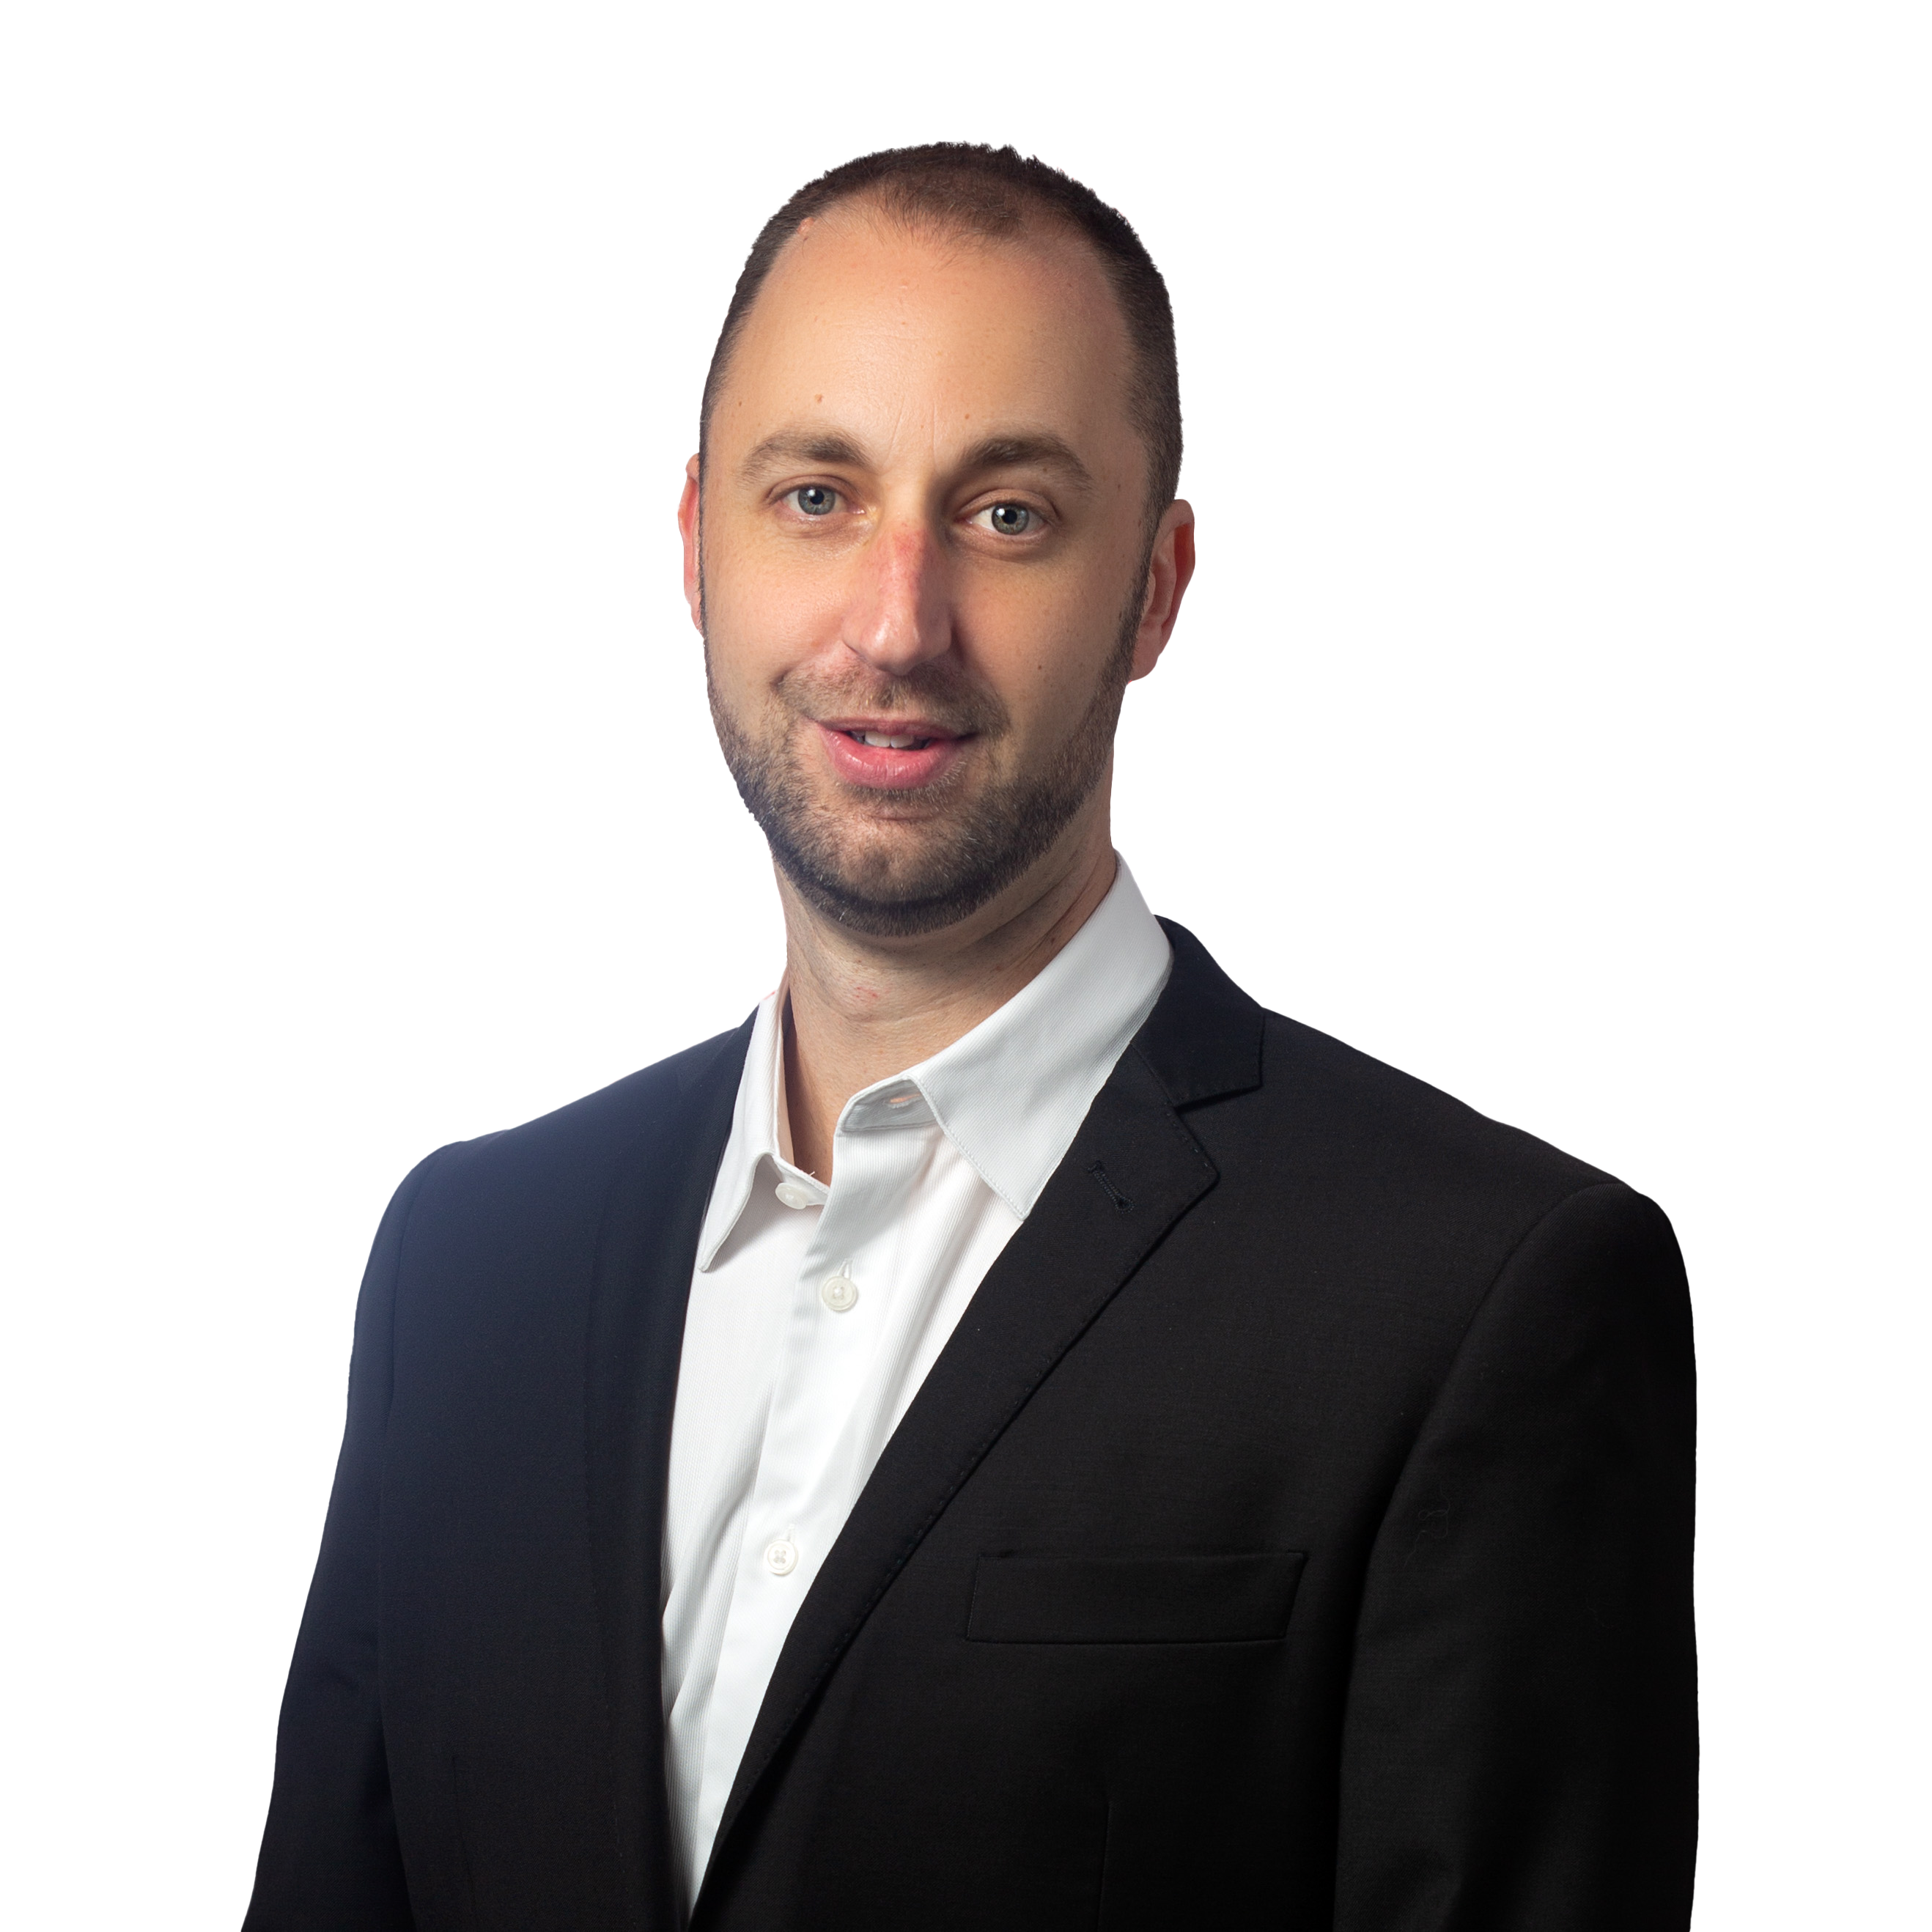
Chris Brown of New Vision Group
New Vision Group is the parent company of 16 brands, spanning finance, real estate, legal services, insurance, property, technology and marketing. Its portfolio includes Sydney-based brokerage New Vision Financial, where Brown serves as managing director and mortgage broker.
The firm works with clients nationwide across home loans, investment properties, refinancing, low-doc and self-employed loans, asset finance and business loans. Brown is also a real estate agent.
We caught up with the broker-founder to hear more about what he's seeing in the market, including in Sydney, how he's navigating a volatile market, and the best practices that have shaped his success as a broker.
The following interview has been edited for grammar and clarity.
CB: Sydney is experiencing a meaningful correction. Figures show dwelling values fell 1.4% in September and were 8.6% below their February peak. That gives buyers a different negotiating environment, but it does not automatically make purchasing affordable. My view is that the key issue is the relationship between the purchase price and the cost of financing it. A lower price can be offset by higher repayments or reduced borrowing capacity.
Sydney's challenges are often amplified by the size of the financial commitment involved. Deposits, transaction costs and mortgage repayments can place considerable pressure on households. Buyers also have to weigh affordability against access to employment, schools and transport. In areas such as the Hills District and Sydney’s northwest, I would encourage buyers to assess the individual property and their own time horizon carefully. A citywide headline cannot tell you whether a particular purchase is suitable.
For investors, the analysis needs to include realistic rent, maintenance, vacancy, insurance and other holding costs. The property has to make sense as an ongoing financial commitment.
CB: As we move through the second half of 2026, the national picture is more cautious. The Reserve Bank of Australia (RBA) has noted that housing prices have fallen in most capital cities and new housing loans have declined noticeably. The Australian Bureau of Statistics (ABS) also recorded a fall in new housing lending in the June quarter. I would separate activity from confidence. People still need to buy homes, relocate and review their finances. But the current conditions make those decisions more demanding.
I would also distinguish enquiries from completed transactions. A borrower may spend considerable time exploring options before being ready or able to proceed. So I would not describe the market as busier simply because there are more conversations.
For brokers, the challenge is helping clients reconcile their objectives with realistic borrowing capacity and repayments. Property valuations, living expenses and lender requirements all need careful attention. My priority is to help clients make decisions they can sustain, including when that means adjusting the budget, changing the timeframe or doing more preparation before purchasing.
CB: I approach uncertainty through preparation and scenario planning. We cannot control the next interest rate decision, but we can assess how a client’s finances would respond to different outcomes.
The RBA increased the cash rate in September. The latest ABS figures show annual headline inflation and trimmed mean inflation are up. Those conditions reinforce the importance of building some breathing room into a borrowing decision. My advice to would-be homeowners is to establish a realistic budget early, account for the full cost of ownership and retain a cash buffer where possible. I would not build a purchase plan around an assumption that rates will fall or property prices will rise.
For existing borrowers, it is sensible to review the loan and compare the total cost of available options. A lower repayment achieved by extending the loan term may increase the interest paid over time. The federal budget changes to negative gearing and capital gains tax also make coordination with a qualified tax adviser particularly important for investors. Timing and individual circumstances matter, and lending advice needs to sit alongside appropriate tax advice.
For brokers, my recommendation is to maintain current lender knowledge, strengthen application preparation and communicate changes promptly. Within a brokerage, consistent processes and clear explanations help the team support clients calmly when conditions shift.
CB: With clients, my approach is to establish the full picture before recommending a solution. That includes their income, commitments, spending, future plans and comfort with risk. The distinction between what someone can borrow and what they can comfortably afford is essential. I want clients to understand the repayments, the upfront costs and the compromises involved in each option.
With lenders, preparation and transparency matters. A well-presented application should explain the borrower’s circumstances, support the income assessment and address potential concerns upfront. That is particularly important for self-employed borrowers or more complex transactions. I would not claim that other brokers are not doing these things. What differentiates my perspective is the combination of finance and real estate experience, which helps me connect the loan structure with the client’s broader property objectives.
I also see technology as a way to improve communication and reduce administration. Its value is in creating more time for informed conversations and sound professional judgement.