The Reserve Bank of Australia (RBA) is expected to keep the official cash rate at 4.6% for the rest of 2026, according to Bendigo Bank’s October 2026 Economic Update. The forecast follows the central bank’s latest increase, which took the rate to its highest level since 2011.
Bendigo’s update notes the rise was the RBA’s fourth in eight months.
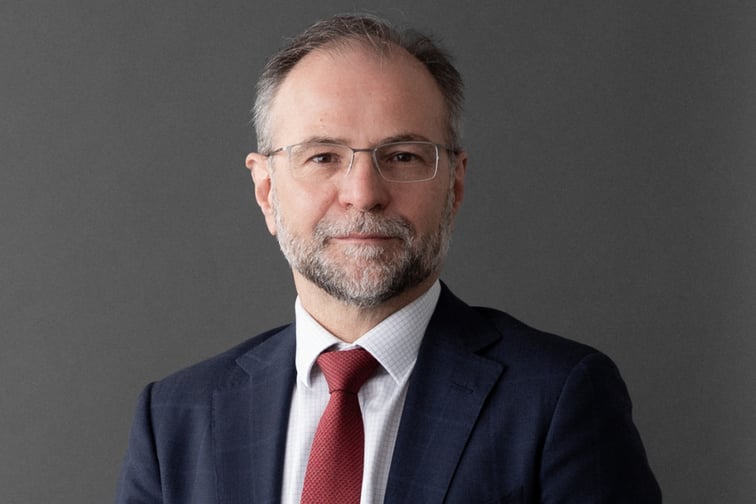
David Robertson (pictured), chief economist at Bendigo Bank, expects no further changes in November or December, provided upcoming jobs and inflation data hold no major surprises.
Robertson was clear that a pause would not mean cuts were close.
Borrowers “should not anticipate rapid easing in the near term”, he said.
Robertson’s case rests on a combination of pressures. High global oil prices and record diesel costs have coincided with a tight labour market, strong government spending, and weak productivity growth. He said the RBA wants consumer price inflation back under 3% during 2027.
He also pointed to a global boom in technology investment, with private companies competing against governments for workers and capital. The Australian dollar has slipped back below 70 US cents on expectations of higher US interest rates in 2027. Share markets, however, keep setting records, which Robertson said reflects confidence that the technology spending will pay off in productivity.
Property prices are softening, transport costs have climbed since temporary fuel excise relief ended in August, and household spending has stalled. Robertson described “a growing strain on family budgets across Australia”, with consumer confidence now more than 12% lower than a year earlier.
The Westpac–Melbourne Institute Consumer Sentiment Index fell 4.7% to 80.4 in October. Just over 80% of people surveyed after the RBA’s decision expect mortgage rates to keep rising over the next year, up from 63% in September.
Westpac takes a different view of what comes next. The bank expects a further increase at the RBA’s 2–3 November meeting, and forecasts the standard variable mortgage rate will exceed 9% for the first time since 2008.
Robertson, for his part, said there were more signs demand was moderating, but the RBA would need to see “a lot more progress with inflation before rates can be lowered”.
Get the hottest and freshest property and mortgage news delivered right into your inbox. Subscribe now to our FREE daily newsletter.