Suburbs with large numbers of recent buyers on high loan-to-value ratios are the most vulnerable if artificial intelligence (AI) disrupts white-collar employment, according to new analysis from data group FoundIt.
The research, reported by The Daily Telegraph, flagged hundreds of “high risk” suburbs, mostly in Melbourne, Sydney, Brisbane, and Perth. It combined government modelling of AI’s impact on jobs with census and mortgage data.
FoundIt found the riskiest areas share two traits: a concentration of white-collar workers in AI-exposed industries, and homeowners carrying large mortgages on recently purchased properties. If job losses hit, the analysis suggests forced sales could follow and drag down local values, even for owners whose jobs aren’t affected.
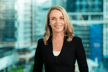
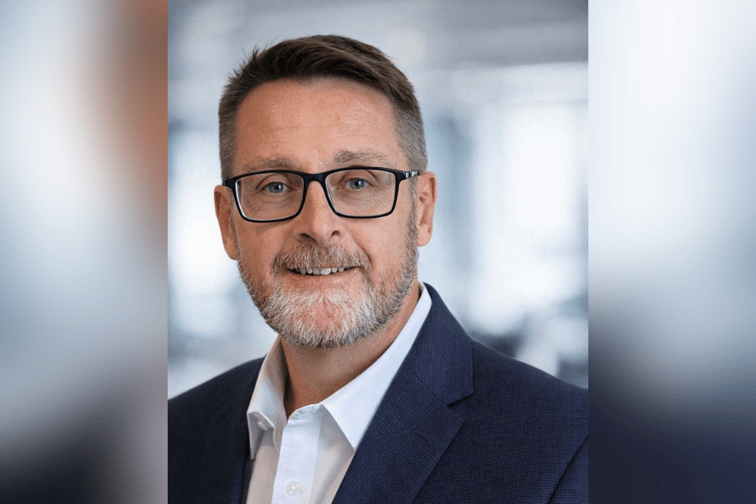
FoundIt head of research Kent Lardner (pictured) said areas with similar job risks but more mortgage-free owners were better placed to absorb a shock.
“Not every suburb housing market will be impacted the same way,” Lardner said.
“The most vulnerable areas have a high number of homeowners relying on white collar wages to pay down a relatively new mortgage with a high loan to value ratio.”
Those borrowers are part of a broader squeeze. Roy Morgan estimates nearly a third of owner-occupier mortgage holders (31.8%) were at risk of mortgage stress in September, and the firm has noted that losing a job poses a bigger threat to repayments than rate rises.
In Sydney, 45 areas were rated high risk, with much of the Hills District and Blacktown singled out. In Kellyville-West, more than half of working residents are managers or professionals, and only 17% of homes are owned outright.
Melbourne had 101 regions facing some level of AI risk, with the inner north expected to be hit hardest. Lardner pointed to the large number of bank and insurance workers in recently bought homes there, and to Victoria’s weaker economy.
Brisbane may be better insulated despite having 15 high-risk suburbs, led by Murarrie, because many recent arrivals came from southern states with substantial equity.
“They didn’t go up there with massive mortgages,” Lardner said.
Lardner said slower wage growth could do more damage than outright redundancies, making it harder for stretched borrowers to escape mortgage stress.
“Suppressed wages is probably the biggest pain point,” he said.
Repayments have kept rising. The Reserve Bank lifted the cash rate to 4.85% on 3 November, its fifth increase this year and its highest level since 2008.
Get the hottest and freshest property and mortgage news delivered right into your inbox. Subscribe now to our FREE daily newsletter.