Just over one in five Australian mortgage holders (22%) expect to be mortgage-free within five years. But 44% either expect to still be repaying their loan in retirement or already are, according to Finder's 2026 Home Loan Report.
The report is based on Finder's July 2026 survey of 1,010 Australian adults, including 291 mortgage holders.
Borrowers' goals vary widely. About a third (34%) want to be mortgage-free as soon as possible, while 41% aim to repay early without being aggressive about it. Only 55% expect to clear their loan before they retire, and income makes a large difference: 76% of those earning more than $200,000 expect to do so, against 25% of those on less than $50,000.
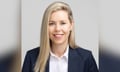
Finder home loans expert Richard Whitten (pictured) said repaying early can pay off.
"Paying off a mortgage early can completely change your financial trajectory," Whitten told realestate.com.au and news.com.au.
The report found 55% of mortgage holders spend more than 30% of their take-home pay on repayments, the traditional mortgage-stress threshold. The average share is 38%.
Just 45% say they could switch to a better loan today. The other 54% say they can't, citing reasons that include their income or expenses, being on a fixed rate, or having too little equity. Separately, 35% believe they couldn't save anything by refinancing.
Canstar research estimates that an owner-occupier who has not renegotiated in five years would be paying about 7.18% after the Reserve Bank (RBA) rate rise widely expected on 29 September. That borrower could save more than $10,000 over two years on a $600,000 loan by switching to a competitive 6.24% rate, even after $1,150 in switch costs.
Whitten urged borrowers not to assume refinancing is out of reach.
"A mortgage broker will run your profile through 20+ lenders," he wrote in the report.
Whitten added that brokers can also show borrowers who aren't yet eligible where they are falling short.
Other Canstar research found a borrower on the average full-time wage of $108,650 could borrow about $11,200 less if the RBA lifts the cash rate again. That would take the total reduction in a typical borrower's capacity this year to $47,400, or about 9%. The estimate is based on an owner-occupier with no other debts, no dependants, and minimal expenses.
Get the hottest and freshest property and mortgage news delivered right into your inbox. Subscribe now to our FREE daily newsletter.