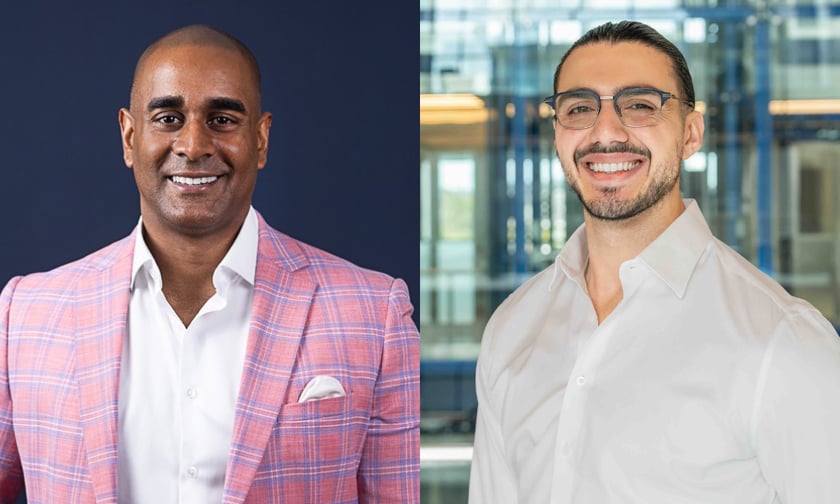
On paper, a senior executive owing $2.4 million on a home worth more than $6 million should be an easy refinance. But the client, who has rolled off a very low fixed rate, was made redundant and has spent more than seven months looking for work. He now cannot refinance at all.
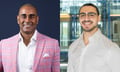
Aaron Christie-David (pictured left), managing director of Atelier Wealth, said more of his clients are failing serviceability when they try to switch lenders than six months ago.
The broker accounts line up with recent data. Equifax figures show switching to a new lender fell 8.8% year on year in September, while refinancing with an existing lender dropped 28%. The Mortgage & Finance Association of Australia’s (MFAA) August 2026 Market Sentiment Survey found 49.2% of brokers had more clients unable to refinance because of serviceability, more than double the 24.4% six months earlier. It reverses an easing trend: in February 2024, 83% of brokers reported greater refinancing difficulty among clients, according to the MFAA. NAB’s latest residential property survey found interest rates were the biggest constraint on established home buyers for a second quarter.
Christie-David pointed to higher rates and softer valuations, along with a rise in redundancies and company restructures over the past three months.
Joseph Daoud (pictured right), founder and chief executive of It’s Simple Finance, said many borrowers contacting his firm took out loans when rates were two points lower and were already at the edge of what they could afford. His typical blocked client has held a loan of $600,000 to $700,000 for at least a year, and many are looking for savings while already on a sharper rate than lenders now offer. Daoud noted that his firm advertises debt consolidation services, so it sees a tougher group of borrowers than the wider market.
Christie-David’s firm has been using lenders that assess like-for-like refinances at a 1% serviceability buffer rather than the standard 3%, an option some lenders began offering in 2023.
“We have been using the 1% refinance buffer, which is such a fantastic policy,” he said.
Daoud said some lenders run 1% buffers, including a Commonwealth Bank pathway that excludes debt consolidation. For harder cases, however, often only high-rate third-tier lenders will approve, and moving a client to a worse rate is not in their best interests, so his advice is sometimes not to refinance.
Existing lenders are also working harder to hold on to borrowers. Daoud described retention teams as noticeably more aggressive, offering bigger discounts and waived annual fees. Christie-David’s firm goes to the current lender first, and where only a few basis points are at stake, he usually advises clients to stay and make additional repayments.
With the Reserve Bank meeting on 3 November, Christie-David expects investors to be hit hardest by a further rise, particularly those rolling off interest-only periods while managing state rental rule changes, a softer market for selling, and loan-to-value or borrowing-capacity barriers.
Daoud said each rate rise widens the gap between what borrowers pay and the rate they are tested at, leaving those who borrowed near their limit, lost equity, or saw their income change most exposed. As he put it: “The worst position isn’t a high rate, it’s a high rate you can’t leave.”
Get the hottest and freshest property and mortgage news delivered right into your inbox. Subscribe now to our FREE daily newsletter.