Ubank has widened its home loan eligibility to include sole traders, allowing self-employed borrowers to apply using their business income and just one year’s tax documents.
The NAB-owned digital bank is promoting the offering through its network of more than 17,000 accredited brokers. Ubank says eligible applications can be approved in around two days through its broker lodgement platform.
Sole traders often struggle to fit standard lending criteria built around PAYG income. Under the new policy, applicants can verify their income with one year’s Individual Tax Return and a matching Australian Taxation Office (ATO) Notice of Assessment.
Borrowers must have held a continuously active Australian Business Number (ABN) for at least two years and show a minimum two-year history of profitable trading. Ubank will lend up to a maximum 80% loan-to-value ratio (LVR) over terms of up to 30 years, and the most recent financial year-end must be no older than 21 months.
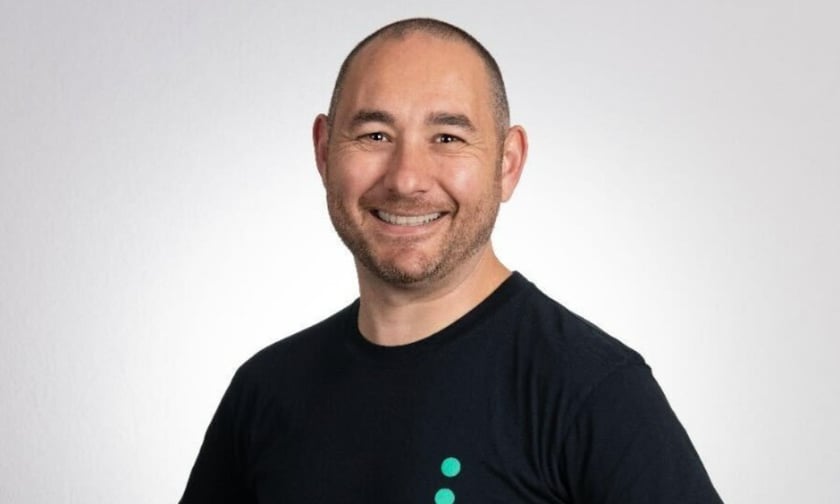
Ubank head of broker distribution George Srbinovski said self-employed borrowers often rely on brokers to navigate lending requirements that don’t fit traditional models.
“Sole traders are a significant and growing customer segment,” he said.
The segment is large. According to the Australian Small Business and Family Enterprise Ombudsman (ASBFEO), nearly 1.7 million Australians operated as sole traders in 2021–22.
The move comes as lenders look for growth in a softer market, with national mortgage demand down 19.2% year on year in September 2026, according to Equifax.
Srbinovski said the offering was aimed at brokers as well as borrowers. “This new offering helps make home lending simpler for eligible sole traders, while giving brokers the confidence of a fast, digital experience,” he said.
For brokers, the change adds another lender option for self-employed clients who may have been turned away elsewhere.
The offering isn’t open to every self-employed borrower. It applies only to sole traders, so clients who run their business through a company or trust aren’t eligible. The 80% LVR cap also means borrowers need a deposit of at least 20%, plus any associated costs.
Eligibility, conditions, and credit criteria apply.
Get the hottest and freshest property and mortgage news delivered right into your inbox. Subscribe now to our FREE daily newsletter.