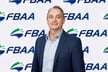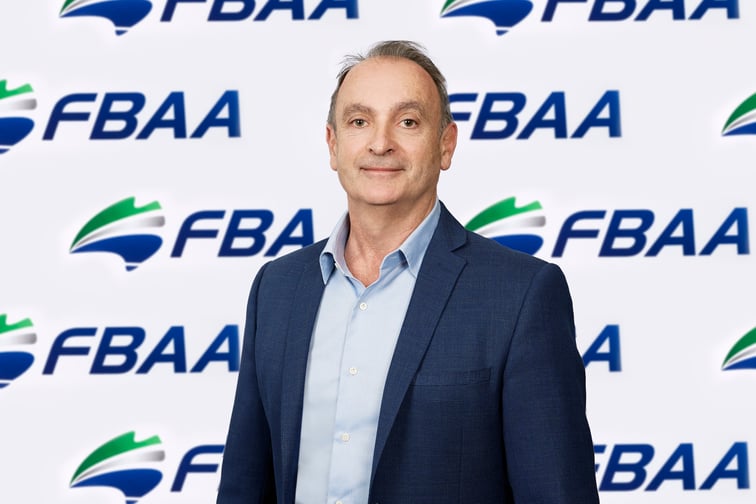
Leo Gagic is coming up on five months at the helm of Finance Broker Association of Australia (FBAA). He was appointed the industry body's chief executive officer in June, taking over from long-time leader Peter White.
In the latest edition of Australian Broker's Spotlight Series — where we shine a light on the individuals shaping Australia's mortgage and finance industries — we're doing something a little different. Across a two-part conversation, we chatted with Gagic about how the lending landscape has evolved, what he has learned since taking the reins at the FBAA, and his views on housing schemes, market volatility, AI and, ultimately, what it takes for brokers to succeed.
"Sustainable growth requires a focus on quality as much as quantity," he told Australian Broker.
The following interview has been edited for grammar and clarity.
LG: The Australian lending industry has undergone remarkable transformation over the past two decades. We have seen brokers move from being viewed as an alternative distribution channel to becoming the primary channel through which Australians access home loans and other finance needs.
The role of the broker has evolved significantly. It is no longer simply about finding a competitive interest rate. Today's brokers guide clients through increasingly complex financial decisions. Regulatory reforms, higher compliance standards, technological advancements and changing consumer expectations have all contributed to a stronger, more professional industry.
What has impressed me most is the industry's resilience and adaptability. Brokers have consistently responded to changing economic conditions, technology shifts and regulatory requirements while continuing to put consumer outcomes first. That professionalism is one of the key reasons broker market share continues to grow.
LG: One of the biggest learnings has been just how passionate brokers are about their profession, and the value they deliver to consumers every day. Across the country, I have met brokers who genuinely care about improving financial outcomes for their clients and communities.
Another key learning is that our industry is changing rapidly, and associations need to evolve alongside it. At FBAA, we have commenced several major transformation initiatives focused on simplifying member experiences, improving our systems and processes, enhancing education offerings and ensuring we remain fit for the future.
I've also learned that members want practical support, strong advocacy, and meaningful engagement. They want an association that listens, responds and helps them navigate an increasingly complex business environment. That is central to our strategic direction.
LG: The most successful brokers are those who focus on the fundamentals. That means maintaining strong client relationships, diversifying revenue streams, investing in professional development and ensuring business processes are efficient and scalable.
Periods of uncertainty often create opportunities. Consumers typically need more guidance when conditions become challenging, whether that's interest rate changes, affordability concerns or lending policy shifts. Brokers who offer guidance rather than solely acting as transaction facilitators are often best placed to thrive. It's also important to remain adaptable. Markets will continue to evolve, and businesses that embrace change rather than resist it will be better positioned for long-term success.
LG: Any initiative that supports greater housing accessibility deserves consideration, particularly when affordability continues to be a major issue for many Australians. However, there is no single solution to Australia's housing challenges. While support schemes can assist certain segments of the market, addressing the housing shortage requires a comprehensive approach that includes increasing housing supply, streamlining planning processes, improving infrastructure and encouraging investment across the housing sector. The industry recognises that demand-side measures can help some buyers enter the market, but long-term affordability challenges will ultimately require meaningful increases in housing supply.
LG: Growth is positive and reflects the trust consumers place in brokers. However, with growth comes responsibility. As broker market share increases, expectations around professionalism, education, compliance and consumer outcomes will continue to rise. The industry must ensure it maintains high standards and continues to invest in capability development.
There is also a need to preserve the personalised service that has helped drive broker success. Consumers increasingly choose brokers because they want guidance, expertise and advocacy. As businesses scale, maintaining that personal connection will remain important. Sustainable growth requires a focus on quality as much as quantity.
LG: Artificial intelligence has the potential to transform the operational side of broking. AI can help streamline administration, improve document collection and verification, assist with customer communications, generate insights and help brokers spend less time on repetitive tasks. The biggest opportunity is not replacing brokers, but enabling them to spend more time doing what they do best: building relationships and providing guidance. Consumers still want confidence, context and human judgment when making significant financial decisions. AI can enhance efficiency, but trust remains fundamentally human. For brokers who embrace the technology responsibly, AI will become an important competitive advantage.