Market chatter has once again turned to private credit, following the collapse of New South Wales property developer Bathla Group, and Australia and New Zealand Banking Group (ANZ) Chief Executive Officer Nuno Matos' subsequent comments on the situation.
The developer was thrust into the spotlight after it entered into voluntary administration last month, carrying more than $3 billion in debt, much of it owed to private-credit lenders. Then, this week, Matos made public comments, saying regulators need to know whether efforts to protect traditional bank depositors are shifting risk into Australia’s less regulated private-credit market.
Private credit has spent years growing in the background of the nation's lending landscape. But with recent events, it's increasingly hard to ignore.
For borrowers unable to meet increasingly stringent bank requirements, private credit can offer another avenue to funding. For investors and lenders, meanwhile, the sector has opened the door to a growing market built around direct lending outside the traditional banking system.
Australia's private credit sector is now estimated to be worth roughly $200 billion. The growth has fundamentally changed the financing landscape, creating opportunities, as well as questions, for brokers navigating the market.
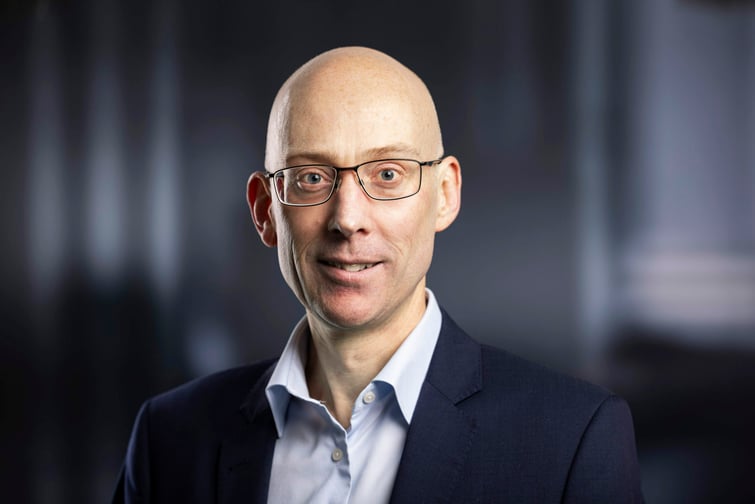
For Australian Broker's latest Spotlight Series — where we highlight stand out professionals in Australia's finance and broking industries — we caught up with Ben Skilbeck, chief executive officer of Australian private credit lender GCI Funds.
The Sydney-headquartered firm offers solutions in property finance, asset-backed finance, business loans and strategic capital.
Skilbeck offers his insights on Australia's growing private credit sector, what brokers need to know and why he believes increased regulatory scrutiny is a good thing.
The following interview has been edited for grammar and clarity.
BS: Private credit also needs to be considered in the context of what it is designed to do. It can provide capital where a bank is constrained by its mandate, capital requirements or inflexible one-size-fits-all lending criteria, particularly for complex mid-market transactions. That does not mean every loan that sits outside the banking system is inherently higher risk. But it does mean borrowers and their brokers need to understand the track record of the lender.
At GCI Funds, we do not take retail money; our investors are wholesale investors and our founders and staff invest alongside them. That alignment, combined with committed capital and disciplined underwriting, is central to how we approach lending.
BS: Increased regulatory scrutiny of private credit funds is a positive development for the industry, particularly where those funds raise money from retail investors. Strong standards around governance, transparency and risk management should apply equally to funds regardless of whether they invest in private assets or market securities. Importantly, private credit is not a homogenous market, and the risks can vary considerably between lenders, strategies and funding models.
BS: For brokers, this makes lender selection increasingly important. The focus should not simply be on rate or leverage, but also on whether the lender has the capital, credit discipline and conviction to deliver what it has offered, and whether the loan meets the borrowers' unique needs.
Capital certainty is particularly important in private credit: a term sheet is only useful if the lender has committed capital available and the ability to complete the transaction. Brokers should be asking prospective lenders where their capital comes from, whether it is committed, how the fund is structured and whether the lender has demonstrated an ability to continue lending through different market conditions.
Anyone can lend when capital is abundant; the more important question is whether a lender can continue to support borrowers when conditions become more demanding. Where a private credit lender has had a material volume of problems in their portfolio, this is likely to impact their ability to fund future loans or to provide flexibility for existing borrowers.