Australian Broker's Spotlight Series— where we highlight standout professionals in Australia's finance and broking landscape — is back.
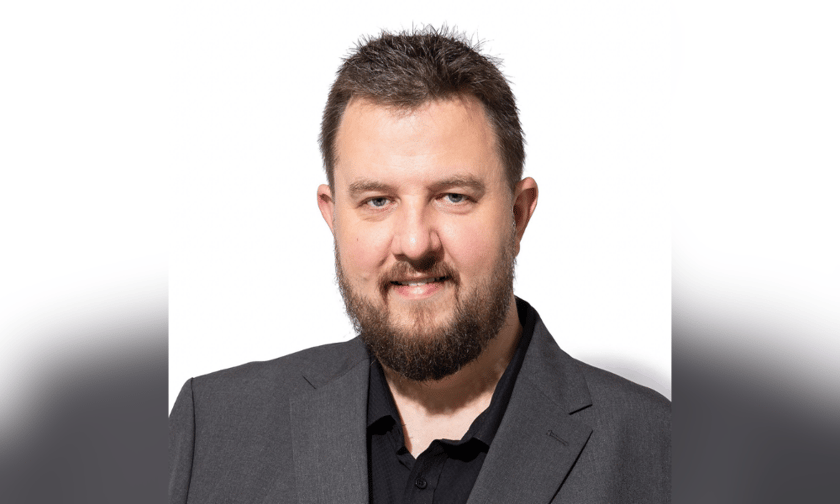
This time, we're turning the spotlight to Shannon Ingram.
Sydney-based Ingram is the founder and principal mortgage broker of Sydney-based brokerage Ingram Financial, which he established in 2024. However, this isn’t his first venture into entrepreneurship. Back in 2010, he founded Smartline, a brokerage he led for six years before eventually selling. Yet, despite moving on from the business, Ingram found that nothing quite "scratched that itch" of broking and helping clients. It was this enduring passion that prompted him to return to the industry in 2024, launching his second brokerage, Ingram Financial.
We caught up with the broker to learn more about his journey, why he's been successful and his thoughts on the ever-evolving Sydney's market.
The following interview has been edited for grammar and clarity.
SI: I started at Australia and New Zealand Banking Group (ANZ) in 2002 as a teller while I was at university, and by 2010 I was running multiple branches in the Sydney central business district (CBD). In 2010 I left to start my own broking business with Smartline. By 2016, the Australian Securities and Investments Commission (ASIC) was reviewing broker remuneration and there was talk of a Royal Commission. I'd watched friends in financial planning see their businesses lose significant value after their industry's reforms, and I'm generally pretty risk-averse. So I sold my business to one of my staff. I then spent eight years running a multi-site window furnishings business. But I honestly regretted leaving. I missed helping clients, especially first-time homebuyers, reach their goals, and nothing else scratched that itch. In 2024, I came back for round two and started Ingram Financial in Bangor, in Sydney's Sutherland Shire.
SI: Big banks run on targets. I remember my branch at Chifley Square [in Sydney's CBD], ranking around seventh in the country, which put it in the top 1%. At the time it was the only Sydney branch in the top 50. But the conversation wasn't about celebrating that. It was about how we'd get to sixth. That's just how large organisations work. But I wanted to measure success by how well clients are looked after, not by the next number. That's what pushed me into my own business in 2010, and it's why Ingram Financial is my own firm today.
SI: Seeing both sides of the table. Eight years in a bank, from the teller line to running branches and handling lending, taught me how an assessor reads a file and where a deal is likely to stall. Running a retail business taught me that service is everything, and that self-employed income is rarely as tidy as a payslip. That said, it's become a lot more straightforward since I came back, with a number of lenders now offering simplified self-employed policies. I'm also quick and efficient. Once I have a client's information and documents, I can often submit their application within hours, and I have systemised follow-ups so I'm on top of every application's status and nothing slips through the cracks. Also, [my advice is] leave your clients with a positive experience, and they will keep coming back to you and referring their friends to you.
SI: Treat broking like a customer business, not a transaction. In retail, every interaction either builds trust or loses it, and finance is no different. Keep clients updated before they have to chase you, and explain why you're recommending a lender, not just which one. When the market changes, get in front of it. When Suncorp Bank closed to new home loans and HSBC announced the sale of its loan book, I wrote plain-English guides for those customers within days, so they had answers before they had to ask. Optimise your processes, but don't optimise away the human connection with your clients. And a good accountant and financial planner are worth their weight in gold. They're not just a referral source. Knowing your clients have the right advice and strategy guiding their journey is invaluable, and the benefits extend well beyond the immediate transaction. Sometimes their advice will differ from what you might have wanted, but when everyone is working in the client's best interests, clients can see that.
SI: Scale is the big one. Even after recent falls, Domain puts Sydney's median house price at around $1.66 million. So deposits, stamp duty and loan sizes are all bigger than in most of the country. Bigger loans run into serviceability buffers and debt-to-income limits much sooner, so borrowing capacity constrains a lot of Sydney buyers, especially first-timers. Locally, the Shire has plenty of bushland, waterfront and flood-affected properties, plus small apartments, and lenders and valuers treat these very differently. Part of my job is knowing which lenders are comfortable with a property before a client falls in love with it.