Lenders offering cashback deals only through selected channels risk damaging their relationships with brokers, the Finance Brokers Association of Australia (FBAA) has warned, as incentives return to prominence in a market where loan applications are under pressure.
The pressure on volumes is clear in the data: Equifax figures show mortgage demand fell 19.2% year on year in September 2026, the weakest result since October 2022.
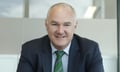
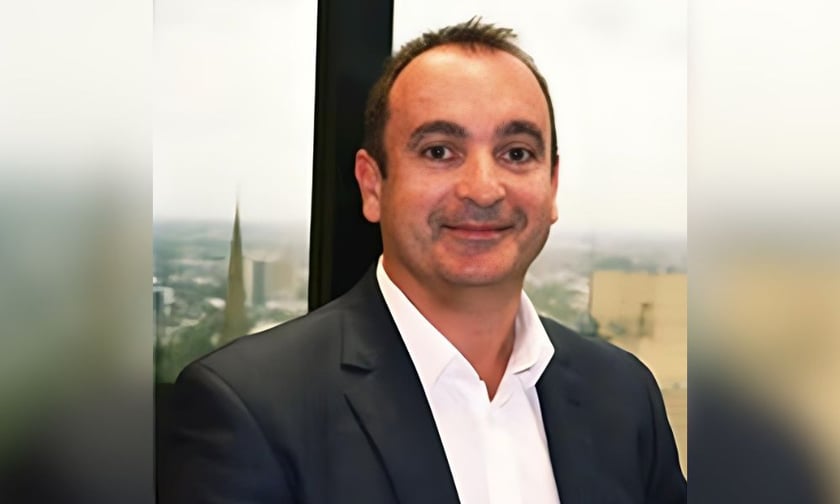
FBAA chief executive Leo Gagic (pictured) acknowledged that a promotional campaign could lift a lender’s volumes in the short term but urged lenders to weigh that against the value of consistent treatment across their distribution networks.
Gagic put it bluntly: “Short-term market share gains should not come at the expense of long-term channel relationships that are fundamental to a competitive and sustainable lending market.”
For brokers, cashback-driven refinancing can carry a direct cost. The median clawback per broker rose 16.5% to $11,442 in 2025, according to the Mortgage & Finance Association of Australia’s (MFAA) State of Mortgage & Finance Broking Report 2026, and MFAA chief executive Anja Pannek has linked past spikes in clawbacks to periods of heavy refinancing, including the earlier “cashback wars”.
Gagic said the FBAA had no objection to lenders using cashbacks and other incentives to win business, provided they stayed within legal and regulatory requirements. His concern was how those offers were structured.
Gagic said: “The issue is not the incentive itself, but ensuring competition occurs in a manner that supports consumer choice and treats all origination channels fairly.”
According to Gagic, problems emerge when an incentive is available through some origination channels but not others, or when one channel receives a materially different offer. In those cases, the risk of conflict between lenders and their distribution partners rises.
That matters to brokers, who originate a significant share of Australian home loans and guide borrowers through an increasingly complicated lending market. The FBAA’s position is that incentive programs work best when they are transparent and accessible across all channels, protecting both borrower choice and the goodwill behind lender-broker partnerships.
Gagic described competition as healthy, saying it drives innovation and better borrower outcomes. But growth targets, he said, should sit alongside fairness, with incentives accessible across broker and direct networks so lenders can compete hard without eroding the partnerships behind a consumer-focused market.
Get the hottest and freshest property and mortgage news delivered right into your inbox. Subscribe now to our FREE daily newsletter.