Sydney's property market remains a challenging landscape for buyers, sellers and existing homeowners alike.
While the harbour city continues to be a highly desirable place to live and work, property ownership remains financially out of reach for many. Meanwhile, falling property prices are adding another layer of complexity to an already challenging market, raising concerns about the value of existing properties and leaving prospective buyers uncertain if they should make a move.
In Sydney, dwelling values were down 4.9%, the largest quarterly decline of an Australian capital city, according to research firm Cotality's October Housing Chart Pack. That's 8.6% below Sydney's February peak.
And outlook could become more challenging still. A survey conducted by the Australian Property Institute found that property prices could drop by as much as 11% below their peak, with a recovery not expected to begin until September 2027.
That's bad news for existing property owners in Sydney, even if they're not looking to sell anytime soon.
Yet falling property prices have done little to encourage prospective homeowners to enter the market, with buyer activity also subdued compared with a year ago.
Higher interest rates, reduced borrowing capacities, persistent inflationary pressures, rising living costs and unemployment, as well as growing market uncertainty and fears about what lies ahead are all part of the problem.
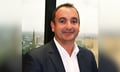
Andrew Hadjidemetri has spent enough time in the Sydney property market to understand the complexities behind these trends.
He opened his own brokerage, Australian Financial and Mortgage Solutions (AFMS) Group, in Sydney in 2020. Although the firm works with clients across Australia, Hadjemetri's experience in the local market gives him a valuable perspective on the distinct challenges facing Sydney and the broader New South Wales property landscape.
"In my view, it'll get worse before it gets better," he told Australian Broker.
For Australian Broker's latest Spotlight Series — where we highlight standout professionals across Australia's finance and broking industries — we caught up with Hadjidemetri once again to hear more about the unique challenges facing the Sydney market and brokers as the 2026 calendar year draws to a close. He also discusses what type of lending is hot at the moment and how he is navigating volatile times.
The following interview has been edited for grammar and clarity.
AH: Sydney is down around 15%, and in my view it'll get worse before it gets better. Factor in two rate increases, one in September and most likely another in November, and you've got less demand meeting more supply, which will hit the market harder. Unemployment will rise, and I expect rates to come down next year.
What else is worth watching too: the 2028 election. If [Australian Prime Minister Anthony] Albanese isn't re-elected, expect a significant swing as some of the current budget measures get reversed. Sydney's biggest ongoing challenge remains affordability. Yes, the median has come down. But you still need a strong income and deposit to get into the market.
AH: It'll get worse before it gets better. The best buying window will likely be 15 November to 15 December, as agents, lawyers and vendors push to close deals before the Christmas shutdown. Activity is different, compared with a year ago. It is lower with the mix now skewed toward refinances and upsizers. Whereas this time last year we saw a lot of investor pre-approvals and strong buyers' agent activity. The biggest challenges for us as brokers right now are serviceability and equity, with valuations coming in lower across the board.
AB: With rate hikes, inflationary pressure, the revised budget and global uncertainty, how do you navigate such volatile times? What's your advice for clients and would-be homeowners? And how do you help brokers prepare?
AH: I expect one more rate rise, in addition to the one in September. My approach is to keep the conversation going with clients. Property remains the preferred asset class because of leverage, security and long-term growth history. Policy will likely shift, much as it did in New Zealand and in Australia back in the 1980s. For existing homeowners who aren't planning to sell, I wouldn't be too concerned; long-term growth history is on your side. But it pays to be realistic: if you bought a $1,000,000 property six months ago with a $950,000 loan under the first-time buyer Home Guarantee Scheme, there's a real chance your loan is now around $940,000 against a property worth closer to $880,000.
AH: Consistent with what I've mentioned above, upsizers and clients pulling equity out via interest-only facilities to position themselves for strong buying opportunities. We're seeing clients purchase near-identical properties today for around 15% less than they would have paid six months ago.